EXPERT CONTRIBUTOR · 10 MIN READ
Ask the head of mortgage broking: before you buy, sell or refinance
We put thirteen questions to the CEO of the Mortgage and Finance Association of Australia, the day after the September rate rise.
The short version
Brokers now write more than eight in ten Australian home loans. For most borrowers they cost nothing to use, because the lender pays them, and they are legally bound to act in the client’s best interests. After the September rate rise, the most useful thing an existing borrower can do is check where their rate sits against what lenders offer new customers.
Key takeaways
- Brokers facilitated a record 81.6% of new home loans in the June 2026 quarter.
- For most home loans and refinances the lender pays the broker, not you.
- Brokers are bound by a best interests duty and must walk away if they cannot meet it.
- Lenders price existing and new customers differently. If you have not checked your rate in three or four years, check it.
- Ask your current lender for a retention offer before you start the refinance paperwork.
- In a fast market, get finance ready before you inspect, not after you find a home.
More than eight in ten Australian home loans now start with a mortgage broker. In the June 2026 quarter, brokers facilitated a record 81.6% of all new residential lending, up from 53.9% in June 2018, according to data from Cotality commissioned by the Mortgage and Finance Association of Australia.
That is a bigger shift than most home owners realise, and it happened in the same years the industry was taken apart and rebuilt by the Royal Commission.
We sat down with Mortgage and Finance Association of Australia CEO Anja Pannek the day after the Reserve Bank lifted the cash rate to 4.60%. Anja has spent more than two decades in the third-party lending channel: CFO of NAB’s Personal Banking division, CEO of aggregator PLAN Australia, and leadership roles at Loan Market Group, Advantedge and Challenger. She has led the MFAA, which represents more than 16,000 brokers and industry professionals, since 2022.
We asked her what home owners get wrong about brokers, what to do after a rate rise, and where finance fits into a property sale. This is the conversation, lightly edited for length.
Why brokers won
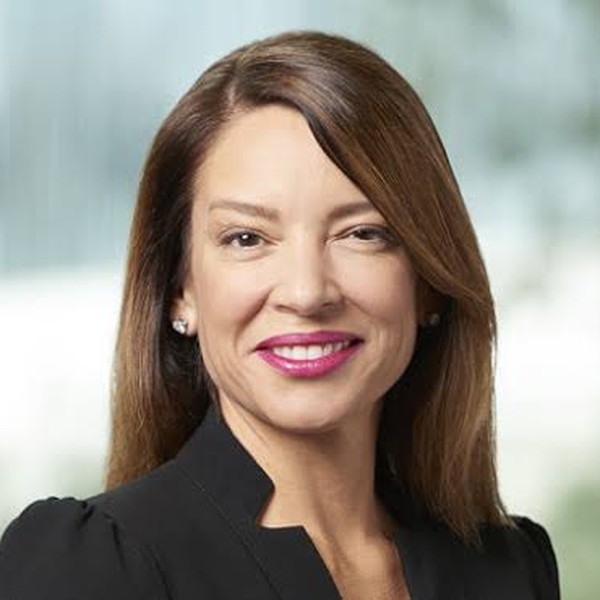
“It feels like the biggest overnight success that has been coming for many, many decades.
“A broker is overwhelmingly a small business. You get up every day, you support your clients, you work with lenders. To run a successful small business in a heavily regulated environment, you have to be highly motivated and believe you can make a difference.
“Then there is the value proposition. A broker is acting for you. They get to know you, often pretty up close and personal around your financials, but also what you want to do with your life. It is a hyper-personalised service. They do the work for you, they are highly skilled, and most brokers have more than 20 lenders on their panel. For any consumer trying to work out where to go next, does it make sense to refinance, will my lender reprice me, it just makes sense to go to an expert.”
Anja Pannek, CEO, MFAAThe Royal Commission
“Since the Royal Commission, I do not know any other industry made up of small businesses that has gone through so much change. The best interests duty, conflicted remuneration, a whole raft of regulation.
“And the industry is now stronger than it has ever been, and more Australians than ever are choosing to use a broker. You do not come through that level of scrutiny and reform unless there is something truly valuable about the industry. For me, that is that the client is right at the centre.”
Anja Pannek, CEO, MFAAWorth sitting on that for a second. The industry was rebuilt around a legal duty to act in the client’s best interests, and its market share went up, not down. More transparency did not cost brokers their customers.
The misunderstanding
“Mortgage broking used to be a transaction sport, but that was decades ago. Today it is anchored in the relationship you and your family have with your broker.
“It is never too early. Many of our members work with potential first home buyers before they are ready to buy. Brokers invest a lot of time helping people navigate not just the lending system, but the reality of Australia today, which includes low levels of financial and digital literacy. How do I get you ready, how do I help you through the first home buyer schemes, and then through the whole journey. It is never one and done.”
Anja Pannek, CEO, MFAADo you pay a broker?
“That still surprises me. People think they need to pay. For the vast majority of people looking at a home loan or a refinance, you do not.
“The lender pays the broker. That remuneration is heavily regulated, and the broker is bound to act only in your interests. If they cannot act in your interests, they have to walk away from the deal.”
Anja Pannek, CEO, MFAA“We love numbers in finance. AFCA is the ombudsman for Australian consumers. If someone has an issue with any part of financial services that cannot be resolved, they can go to AFCA. Less than half a percent of complaints at AFCA relate to brokers. Given brokers facilitate almost 82% of mortgages, that tells me brokers are living and breathing their obligations.”
Anja Pannek, CEO, MFAAAfter the rate rise
“I do expect lenders will pass on the full 25 basis points.
“What will be interesting is the gap between the back book and the front book. If your mortgage has already settled, you are on the back book. A new customer is the front book. With lower transaction activity, will lenders sharpen their new lending rates to drive acquisition?
“That is why it is so important to speak to your broker and understand where you sit relative to the market. If you have had your mortgage for three or four years and you have not spoken to anyone, go and talk to your broker and understand your options. A lot of economists are talking about another rise, because inflation is so sticky.”
Anja Pannek, CEO, MFAABen’s insight: your rate is not set by the RBA. It is set by your lender, and lenders price existing customers and new customers differently. If you have not checked your rate since you settled, the gap is very unlikely to be in your favour.
Our breakdown of the September rate rise has the numbers.
The refinance trap
“Why isn’t it easier for a borrower to discharge their home loan?
“Australia has one of the most digitised home loan application and approval processes anywhere. But the discharge process at many lenders, including many of the majors, still means finding a form somewhere on the website, and in some cases wet signing it. In 2026. I think that is crazy.
“What we see is friction put in the process. The broker will ask the current lender for a better price first, because staying might be the best outcome. Then, two seconds before the discharge, the lender comes back with a better offer, sometimes even cash back.
“So we are pushing for a standardised, visible discharge form, for lenders to let the broker act for the client in the discharge, and for discharges to happen within 10 days.”
Anja Pannek, CEO, MFAAThe lesson for a borrower is simple: ask for the retention offer before you start the paperwork, not after. Your lender can usually find a better rate. It is just more motivated to find it once you are leaving.
The 10-day discharge and the standard form were both recommendations of the ACCC’s 2020 Home Loan Price Inquiry. The MFAA set out the case in its 2024 white paper on home loan discharges.
First home buyers
“The expansion of the 5% Deposit Scheme brought a significant uptake and many new first home buyers into the market, at a time when the property market was running incredibly hot.
“First home buyers are finding opportunities, and prices have come down, mainly in the higher price brackets. But their borrowing capacity has been reduced with each rate rise.
“The challenge for Australia remains structural, and it is supply. We have high inflation, competing demand for construction capability with things like data centres, and a higher interest rate environment. We need a whole lot of different solutions to help with home ownership, and I think we will see more product innovation outside the government schemes too.”
Anja Pannek, CEO, MFAAWhere finance fits in a property sale
“It depends on the relationship. Many organisations have realised that a key element of the property journey is financing, and how to bring it in at the right time. Some do that very well. For others it has been a challenge.
“A real estate agent’s number one focus is getting the best outcome for their client. A broker’s number one focus is making sure their client is finance ready. There is absolute alignment between the two.
“Look at Perth and WA over the last year, where the time from listing to sale was among the tightest in the country. You would be crazy to start looking for a property unless you were finance ready. Pre-approvals, the right structure, the right lender, whether you need bridging finance. In the US that relationship is a lot tighter than here, so there is a big opportunity.”
Anja Pannek, CEO, MFAAThis is the part of the interview we think about most at Unreserved. A property sale is full of moments where someone needs finance help and nobody offers it: the buyer who enquires without pre-approval, the seller who is also buying and has not thought about bridging, the offer that arrives subject to finance with a 14-day window. We are building our platform to spot those moments and connect people with a broker early, with their consent.
If you are selling and buying at once, our guide to whether to buy or sell first covers the finance side.
AI and trust
“Like every industry, the biggest thing we are grappling with is how fast technology is moving.
“Consumers are using AI to research. Members tell me a client comes in and says, I have done all this research, why is this not the best for me? It takes some re-education to work back from that.
“The opportunity is to keep elevating the truly human parts of broking, sitting in front of a person and giving them confidence, because these are big decisions. It is a 20 or 30 year commitment, but it is really about where do I want to live, what do I want for my family, is this right for my long-term wealth. And the industry can take advantage of the technology in a way that is safe and ethical, because brokers handle vast amounts of data. It all comes back to trust.”
Anja Pannek, CEO, MFAAWe agree with more of that than you might expect from a company built on AI. Software is very good at comparing 30 products in a second. It is not yet good at telling you whether you should be buying at all.
If you were starting today
“Unless I had a banking background, I would go and work in a broking firm where I would have the right support around me.
“Then, once you have done your mentorship and your qualifications, be really clear about your customer value proposition. It is a big market. Where do you want to focus first and create value? And then, who are the right referral partners to help you get there, and how do you create value both ways?”
Anja Pannek, CEO, MFAAThe short version
| What people assume | What is actually true |
|---|---|
| You pay a broker to find you a loan | For most home loans and refinances, the lender pays the broker, and that pay is regulated |
| A broker just finds the cheapest rate | Brokers are bound by a best interests duty and must walk away if they cannot meet it |
| Your rate moves with the RBA and that is that | Lenders price existing and new customers differently; check where you sit |
| Refinancing means leaving | Your current lender will often match or beat an offer, so ask first |
| You get finance sorted once you find a home | In a fast market, being finance ready comes before inspections, not after |
Five things home owners assume about mortgage brokers, and what is actually true.
If you are getting ready to sell, start with our guide to the process of selling a house.
Know what your home is worth first.
Whether you are refinancing, upgrading or selling, the number your lender and your buyer care about is the value of the property. Our instant estimate is free, takes about a minute, and comes with a confidence rating.
Get an instant estimateGeneral information, not financial advice, current as at October 2026. Speak to a licensed mortgage broker about your own situation.
EXPERT CONTRIBUTOR
Anja Pannek
Anja Pannek is CEO of the Mortgage and Finance Association of Australia, the peak body for mortgage and finance brokers, representing more than 16,000 members. Before joining the MFAA in 2022 she was CEO of PLAN Australia and CFO of NAB’s Personal Banking division, with leadership roles at Loan Market Group, Advantedge and Challenger. Her comments in this article are general information, not financial advice.